Last updated
How to build credit at 18 without falling into a credit card trap
| Option | How it works | What to watch | Proof |
|---|---|---|---|
| Secured credit card | You put down cash, for example $500, and that sets your limit | Fees and rates vary and can be high. Ask if it reports to the bureaus | B, CFPB guidance |
| Credit-builder loan | You pay over 6 to 24 months while the lender holds the money in savings, then you get it back | Only helps if the lender reports to the bureaus | B, CFPB guidance |
| Authorized user on a parent's card | You are added to someone else's card | May not build your own history. Their missed payments can hurt you both | B, CFPB guidance |
| Your own card before 21 | Needs your own income or a cosigner who is 21 or older | A cosigner owes your whole balance if you do not pay | A, CARD Act |
| Buy Now, Pay Later | A purchase split into payments, often with no interest | Late fees, overdrafts from auto-pay, collections if missed | B, CFPB guidance |
| Debit card or prepaid card | Spends your own money | Does not build credit | B, CFPB guidance |
Reading the credit options side by side
The table lists every common way an 18-year-old hears about for starting credit. Read the third column first. That is where each one can go wrong.
The two that were built for an empty credit file are at the top. A secured card is a real credit card, but your own cash sets the limit. A credit-builder loan works backward: you make the payments first and get the money at the end.
Both share one catch. They only help if the lender reports your payments to the credit bureaus. The CFPB page on starting a credit history says to ask before you sign up. So ask, in those words: do you report to all three bureaus?
The under-21 rule that explains a no
You applied for a card and got turned down. It may not be about you at all.
Under federal law, a card company can't open an account for someone under 21 unless you show you can pay on your own, or someone 21 or older cosigns in writing. The CFPB explains the age rule here.
If a parent cosigns, they owe your balance if you don't pay it. That is a big ask. Treat it like one.
Three things that look like credit and are not
A debit card. It spends money you already have. It does not build credit.
Paying off a payday loan. Payday lenders generally don't report on-time payments to the nationwide bureaus. And a typical one costs about $15 for every $100 for two weeks, close to 400 percent a year.
Buy Now, Pay Later on time. It is a real loan with a schedule. Missed payments can go to collections. In a CFPB report, 4.1 percent of these loans in 2023 were charged a late fee.
The offer that showed up in your feed
It is a Tuesday. An ad says you are pre-approved. Another app offers to split your sneakers into four payments. Your friend says you need to carry a balance to build credit.
None of these is the trap by itself. The trap is not knowing the rules when you say yes. Carrying a balance does nothing good for your score. It just costs interest.
What counts most is boring: paying on time, every month. FICO says that is 35 percent of its score. A late payment stays on your report for seven years. Autopay for at least the minimum takes ten minutes to set up and protects the biggest piece.
Protect the credit you are building
A new credit file is worth guarding. The book's credit chapter and its scam chapter work as a pair.
Pull your free reports from all three bureaus at AnnualCreditReport.com. At 18 your report may be empty, which is normal. Then freeze your credit at all three bureaus. A freeze has been free since September 2018 and does not touch your score. When you apply for a card or an apartment, you lift it, apply, and freeze it again.
If a friend asks you to cosign their loan, read our page on what to check before a first lease first. The cosigner rule there is the same one.
Where the book covers credit
This is the problem The 18 Manual was written for. Iris Athens grades every move, so you can tell a federal rule from a guess.
Credit Without the Trap has eleven moves, from pulling your reports to the under-21 rule, secured cards, Buy Now, Pay Later and why you should not cosign for a friend. It also busts five myths, each next to the official source that settles it.
Scams and Your Identity covers the credit freeze, fraud alerts and what to do if accounts you never opened show up on your report.
The book does not name a card or a lender, and it is not financial advice. For a question about your own report, the CFPB at consumerfinance.gov and the credit bureaus are where to check.
The book for this problem
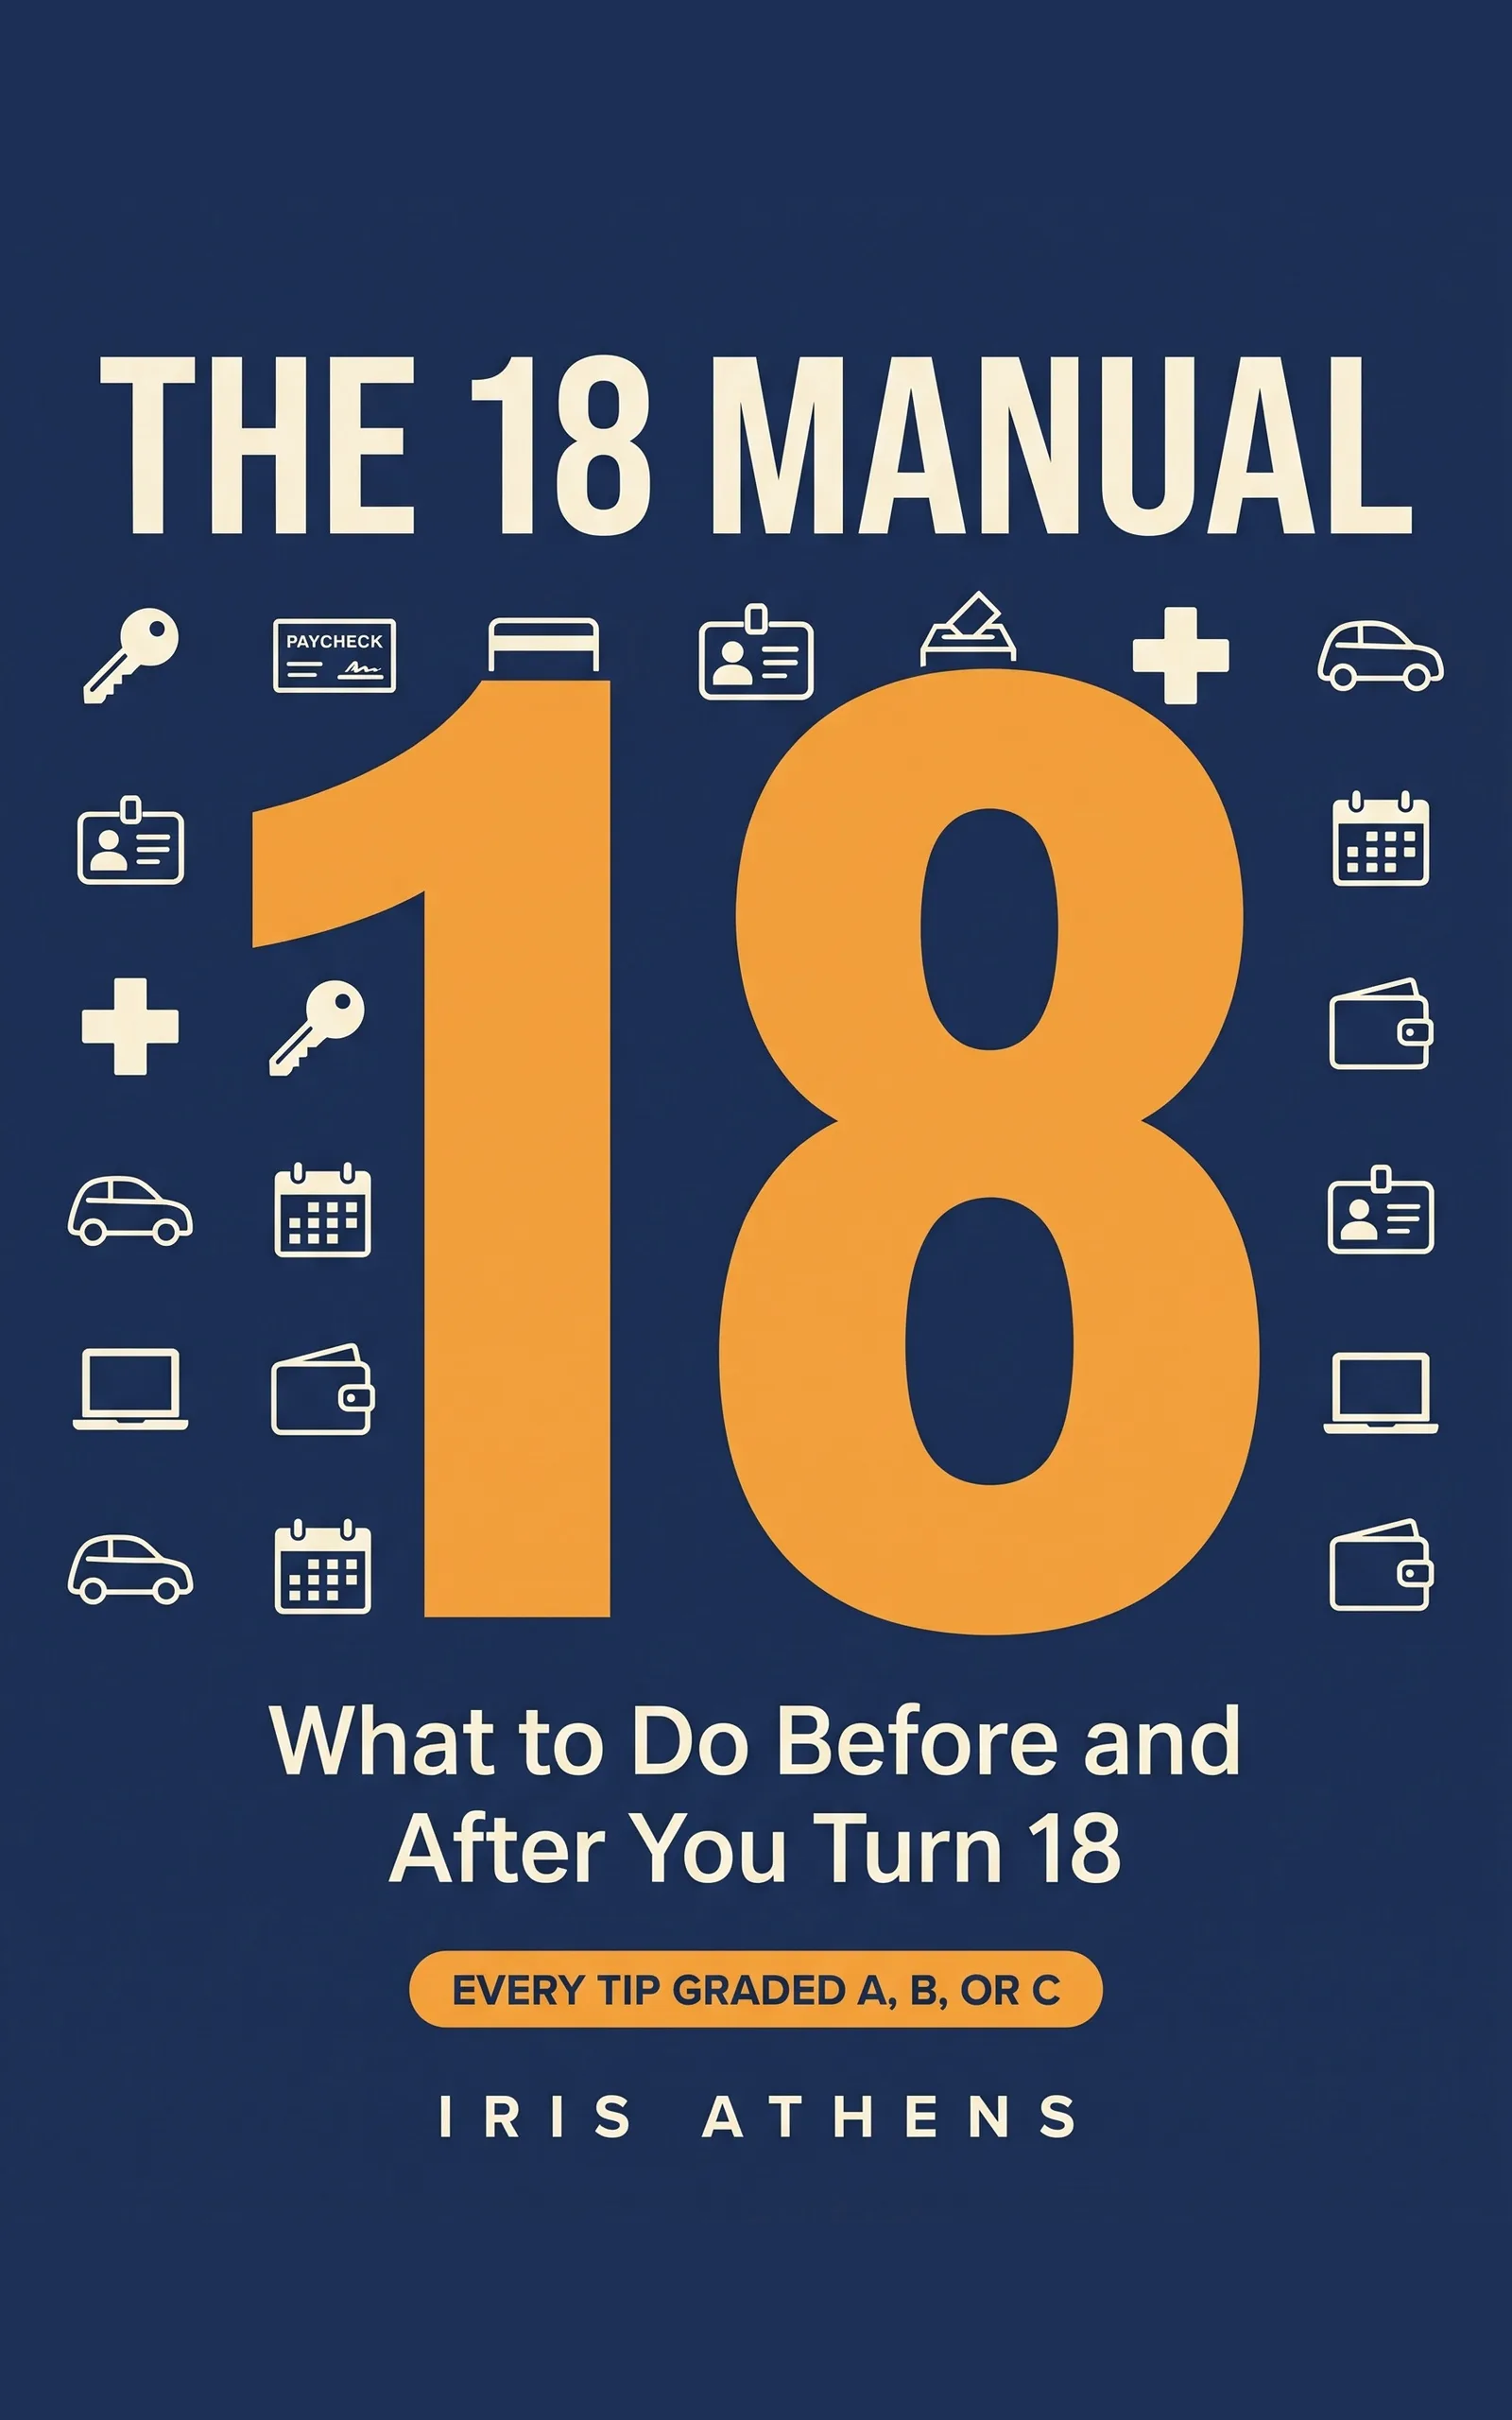
The 18 Manual
What to Do Before and After You Turn 18: Money, Work, Rent, Health, and Your Legal Rights, Graded by What It Costs and How Well It Works. By Iris Athens, 142 pages.
Where this problem is in the book:
- Credit Without the Trap
- Scams and Your Identity
Links go to Amazon. ToolGenX publishes this book under a pen name and earns from every sale. Amazon sets the price and handles delivery and returns.
Is The 18 Manual the right book for you?
Yes, if
- You are 18 or 19 with an empty credit report
- Card offers keep showing up and you want to know the rules first
- A parent offered to add you to their card and you want to know what it does
Skip it if
- You want someone to pick a card or a lender for you
- You already carry card debt and need a plan to pay it off
Fair doubts before you buy
Can't I just get a card and pay it off every month?
You can, if you qualify. Under 21, federal law says a card issuer needs proof you can pay on your own, or a cosigner who is 21 or older. Many 18-year-olds have neither. That is why the secured card and the credit-builder loan exist.
Is this not just what the bank tells you?
Some of it is. The difference is that every option here carries a grade. The under-21 rule is an A, a federal law. The 30 percent advice about card balances is a C, a rule of thumb with no official cutoff. We show both so you know which one to trust more.
Get The 18 Manual
About 130 grown-up moves, from a first bank account to a first lease, each graded by what it costs and how well it works, so a new 18-year-old knows which ones are worth the time.
Links go to Amazon. ToolGenX publishes this book under a pen name and earns from every sale. Amazon sets the price and handles delivery and returns.
This book explains published US rules and where to check them. It is not legal, tax, medical or financial advice.
Questions people ask about this
- What is the fastest way to build credit at 18?
- There is no shortcut the official guidance backs. FICO says payment history is 35 percent of its score, the biggest piece. A secured card or a credit-builder loan that reports to the bureaus, paid on time every month, is how a first credit file starts. Opening several accounts in a short time looks riskier.
- Does a debit card build credit?
- No. Neither do prepaid cards, cash or, as a general rule, payday loans. Payday lenders generally do not report on-time payments to the nationwide credit bureaus. Only credit that is reported to the bureaus builds a credit history.
- Can you get a credit card at 18 with no job?
- Under 21, a card issuer can only open an account if you show an independent ability to pay, or if a cosigner or joint applicant who is 21 or older agrees in writing to owe the debt. The same rule applies to limit increases before 21. Anyone who cosigns is legally on the hook for your balance.
- Does being an authorized user build credit?
- Not always. The CFPB says being an authorized user won't necessarily help you build your own credit history. Only the main cardholder is legally responsible for the bill, and if they miss payments, it can hurt both of you.
- Does checking your own credit hurt your score?
- No. Pulling your own report is a soft inquiry, and the CFPB says it does not hurt your credit score. You can get free reports from Equifax, Experian and TransUnion at AnnualCreditReport.com, the only site authorized for them.
- Do you need to carry a balance to build credit?
- No. That is a myth. Paying the full statement balance by the due date avoids interest on new purchases if your card has a grace period. What builds your score is a record of paying on time. In August 2026, the average card rate on accounts charged interest was 22.36 percent.
Related problems
- First apartment at 18: what to know before you sign the lease
About to rent your first apartment at 18? What to check in the lease, how to get your deposit back, renters insurance and the signs of a fake listing.
- Sent money to a scammer? What to do right now, step by step
Just sent money to a scammer? Call the payment company today, then report it. The steps for gift cards, fake checks, stolen IDs and photo threats.
- What changes legally when you turn 18, and what to do in that first week
At 18 your contracts count, your medical records become yours and men must register with Selective Service. See each rule with its proof grade.
- Everything inside The 18 Manual
Every chapter, who the book is for, and every problem it helps with.
// Also on this topic
- guideSecrets vs. surprises: how to explain the difference to your child without scaring them
A calm way to teach kids 8 to 12 the difference between a surprise and a secret, which secrets they always tell, and the words to say.
- guideYour child is being bullied and goes back to school tomorrow. What should they say to the bully?
Your child is being bullied and school is tomorrow. The calm words to say, what to do next, and how to report it if telling once did not work.
- bookWhat Do I Say If...?
The Street-Smart Phrasebook for Kids 8-12: The Exact Words to Say No, Get Help, and Stay Safe With Strangers, Friends, Bullies, and People Online