Last updated
What to do 3 months before turning 65: a month-by-month Medicare checklist
| When | What to do | Why it matters |
|---|---|---|
| 12 months before your birthday month | Work out which kind of 65 you are. Ask your employer, in writing, about its size for Medicare | Whether you sign up yourself, and whether job coverage lets Part B wait |
| 10 months before | Check your earnings record and credit count. Ask Social Security about any wrong years | 40 credits means no Part A premium. In 2026, buying Part A costs $311 or $565 a month |
| Before you apply, if you have an HSA | Work out your last month to contribute. Tell the benefits office when to stop deposits | Part A can reach back up to 6 months. Money put in for those months is excess |
| 3 months before (the window opens) | Sign up, or confirm automatic sign-up. Check if your drug coverage is creditable and keep the letter. Gather doctors, prescriptions and travel plans | Signing up now means Part B starts in your birthday month |
| Your birthday month | Check that the card arrived and the details are right. Confirm start dates. Note your Medigap window if you chose Original Medicare | The 6-month Medigap window starts the first month you have Part B at 65 or older |
| The 3 months after | If you have not signed up, the window is still open | Part B starts the month after you sign up |
| After your birthday month | Put your spouse's own dates on the calendar. Check any income surcharge letter | Each spouse has a separate window. The surcharge uses a tax return from 2 years ago |
Reading the checklist from top to bottom
The table runs on one date: your birthday month. Every row counts from it. If your birthday is on the 1st, Medicare treats you as turning 65 a month early, so move every row back one month.
The row you are in now is the one marked "3 months before." That is when the seven-month window opens. Medicare calls it the Initial Enrollment Period.
The rows above it are things the book puts earlier, a year out and ten months out. If you skipped them, do them now. Checking your earnings record still matters, because it decides whether Part A costs you nothing.
The rows below it are what comes next. Your birthday month, the three months after, and the clocks that keep running once you have Medicare.
Three months out: the three jobs for this month
Sign up, or confirm. If you are getting Social Security or Railroad Retirement benefits, and they started at least 4 months before you turn 65, Medicare signs you up on its own. If not, you sign up through Social Security, online at SSA.gov/medicare/sign-up or by appointment. You can contact them 3 months before you turn 65 to set one up.
Check your drug coverage. Part D, the drug coverage, runs on this same window. If you have drug coverage through a job or union, the plan must tell you whether it is "creditable," meaning Medicare counts it as at least as good as standard Part D. Keep that letter. Medicare's page on the Part D late enrollment penalty explains what happens without it.
Gather your list. Before you compare Original Medicare and Medicare Advantage, write down your doctors and hospitals, your prescriptions with doses, and where you spend time each year. Medicare's Plan Finder is at Medicare.gov/plan-compare.
And one small job that saves trouble later. Keep proof of the date you signed up. Save the online confirmation. If you call, write down the name of the person you spoke with.
If your card arrives and you want to wait on Part B
If Medicare signs you up on its own, the card can arrive about 3 months before coverage starts. Some people still covered by a current job want to wait on Part B. The book gives Social Security's two deadlines for saying no.
- If you got the welcome package with your card, you must refuse Part B before the start date printed on the card.
- If you got a Medicare award notice, a letter confirming your Medicare, you have two full calendar months after the date on that letter.
The refusal has to be in writing. If it arrives late, Social Security treats it as canceling Part B, and Part B ends at the end of the following month. Saying no can lead to a late penalty unless you have the right kind of coverage in its place, so read our page on still working at 65 first.
If your coverage now is COBRA or a retiree plan
This is the row people get wrong most often. COBRA and retiree plans feel like your old job's insurance, but Medicare does not count them as coverage from current work.
That means two things. Once you are eligible, Medicare pays first, and the old plan pays second. And when COBRA or the retiree plan ends, no new window opens to sign up for Part B. So if this is your path, the seven-month window around your birthday is the one to use.
Ask your COBRA or retiree plan what it will pay once you are eligible for Medicare. Most retiree plans expect you to sign up as soon as you can.
The calendar on the fridge
You put a sticky note on the fridge that says "Medicare." That was a month ago. It is still there, curling at the edges.
Every time you walk past, you feel a little behind. Not because you did anything wrong. Because nobody handed you a list, and the mail is full of ads that all want a different first step.
Here is the honest part. You don't have to learn all of Medicare this month. You need the three jobs above, and the dates for the rows below them. This page centers on that one row, and we chose it for a reason: it is the month the window opens, and it is the month most worth getting right.
The Medicare & You 2027 handbook is the official reference for every step on the list.
What waits for your birthday month and after
When your birthday month comes, check the card. Read what it says. Guard the Medicare Number. Note the start dates for Part A and Part B.
If you chose Original Medicare, mark your Medigap window. It lasts 6 months from the first month you have Part B and are 65 or older, and it comes once.
After that, two more clocks. If you are married, your spouse has a separate window built around their own birthday. And if a letter says your Part B premium is higher because of income, that surcharge is built from your tax return from 2 years ago. There is a form to ask for a newer year.
The book behind this checklist
This is the problem The Year You Turn 65 was written for. Nancy Whitaker's whole book is sorted by month, so this checklist is its backbone.
Three Months Out: The Seven-Month Window Opens covers the sign-up itself: how to sign up, what each month of the window does, the 2023 rule change and the 1st-of-the-month birthday.
The Same Window: The Drug Coverage Question explains Part D, the 63-day penalty rule with 2026 figures, and the creditable coverage letter.
The Month You Turn 65 is a short checklist for the birthday month itself: the card, the number, how the Part B premium gets paid and the clocks still running.
Your 65 Calendar collects every date and document from the book on fill-in pages, including a month-by-month checklist and a log of everyone you talk to.
The book is not affiliated with Medicare or Social Security. Your State Health Insurance Assistance Program (SHIP) gives free counseling, and Social Security can look at your own file to confirm your sign-up and your start dates.
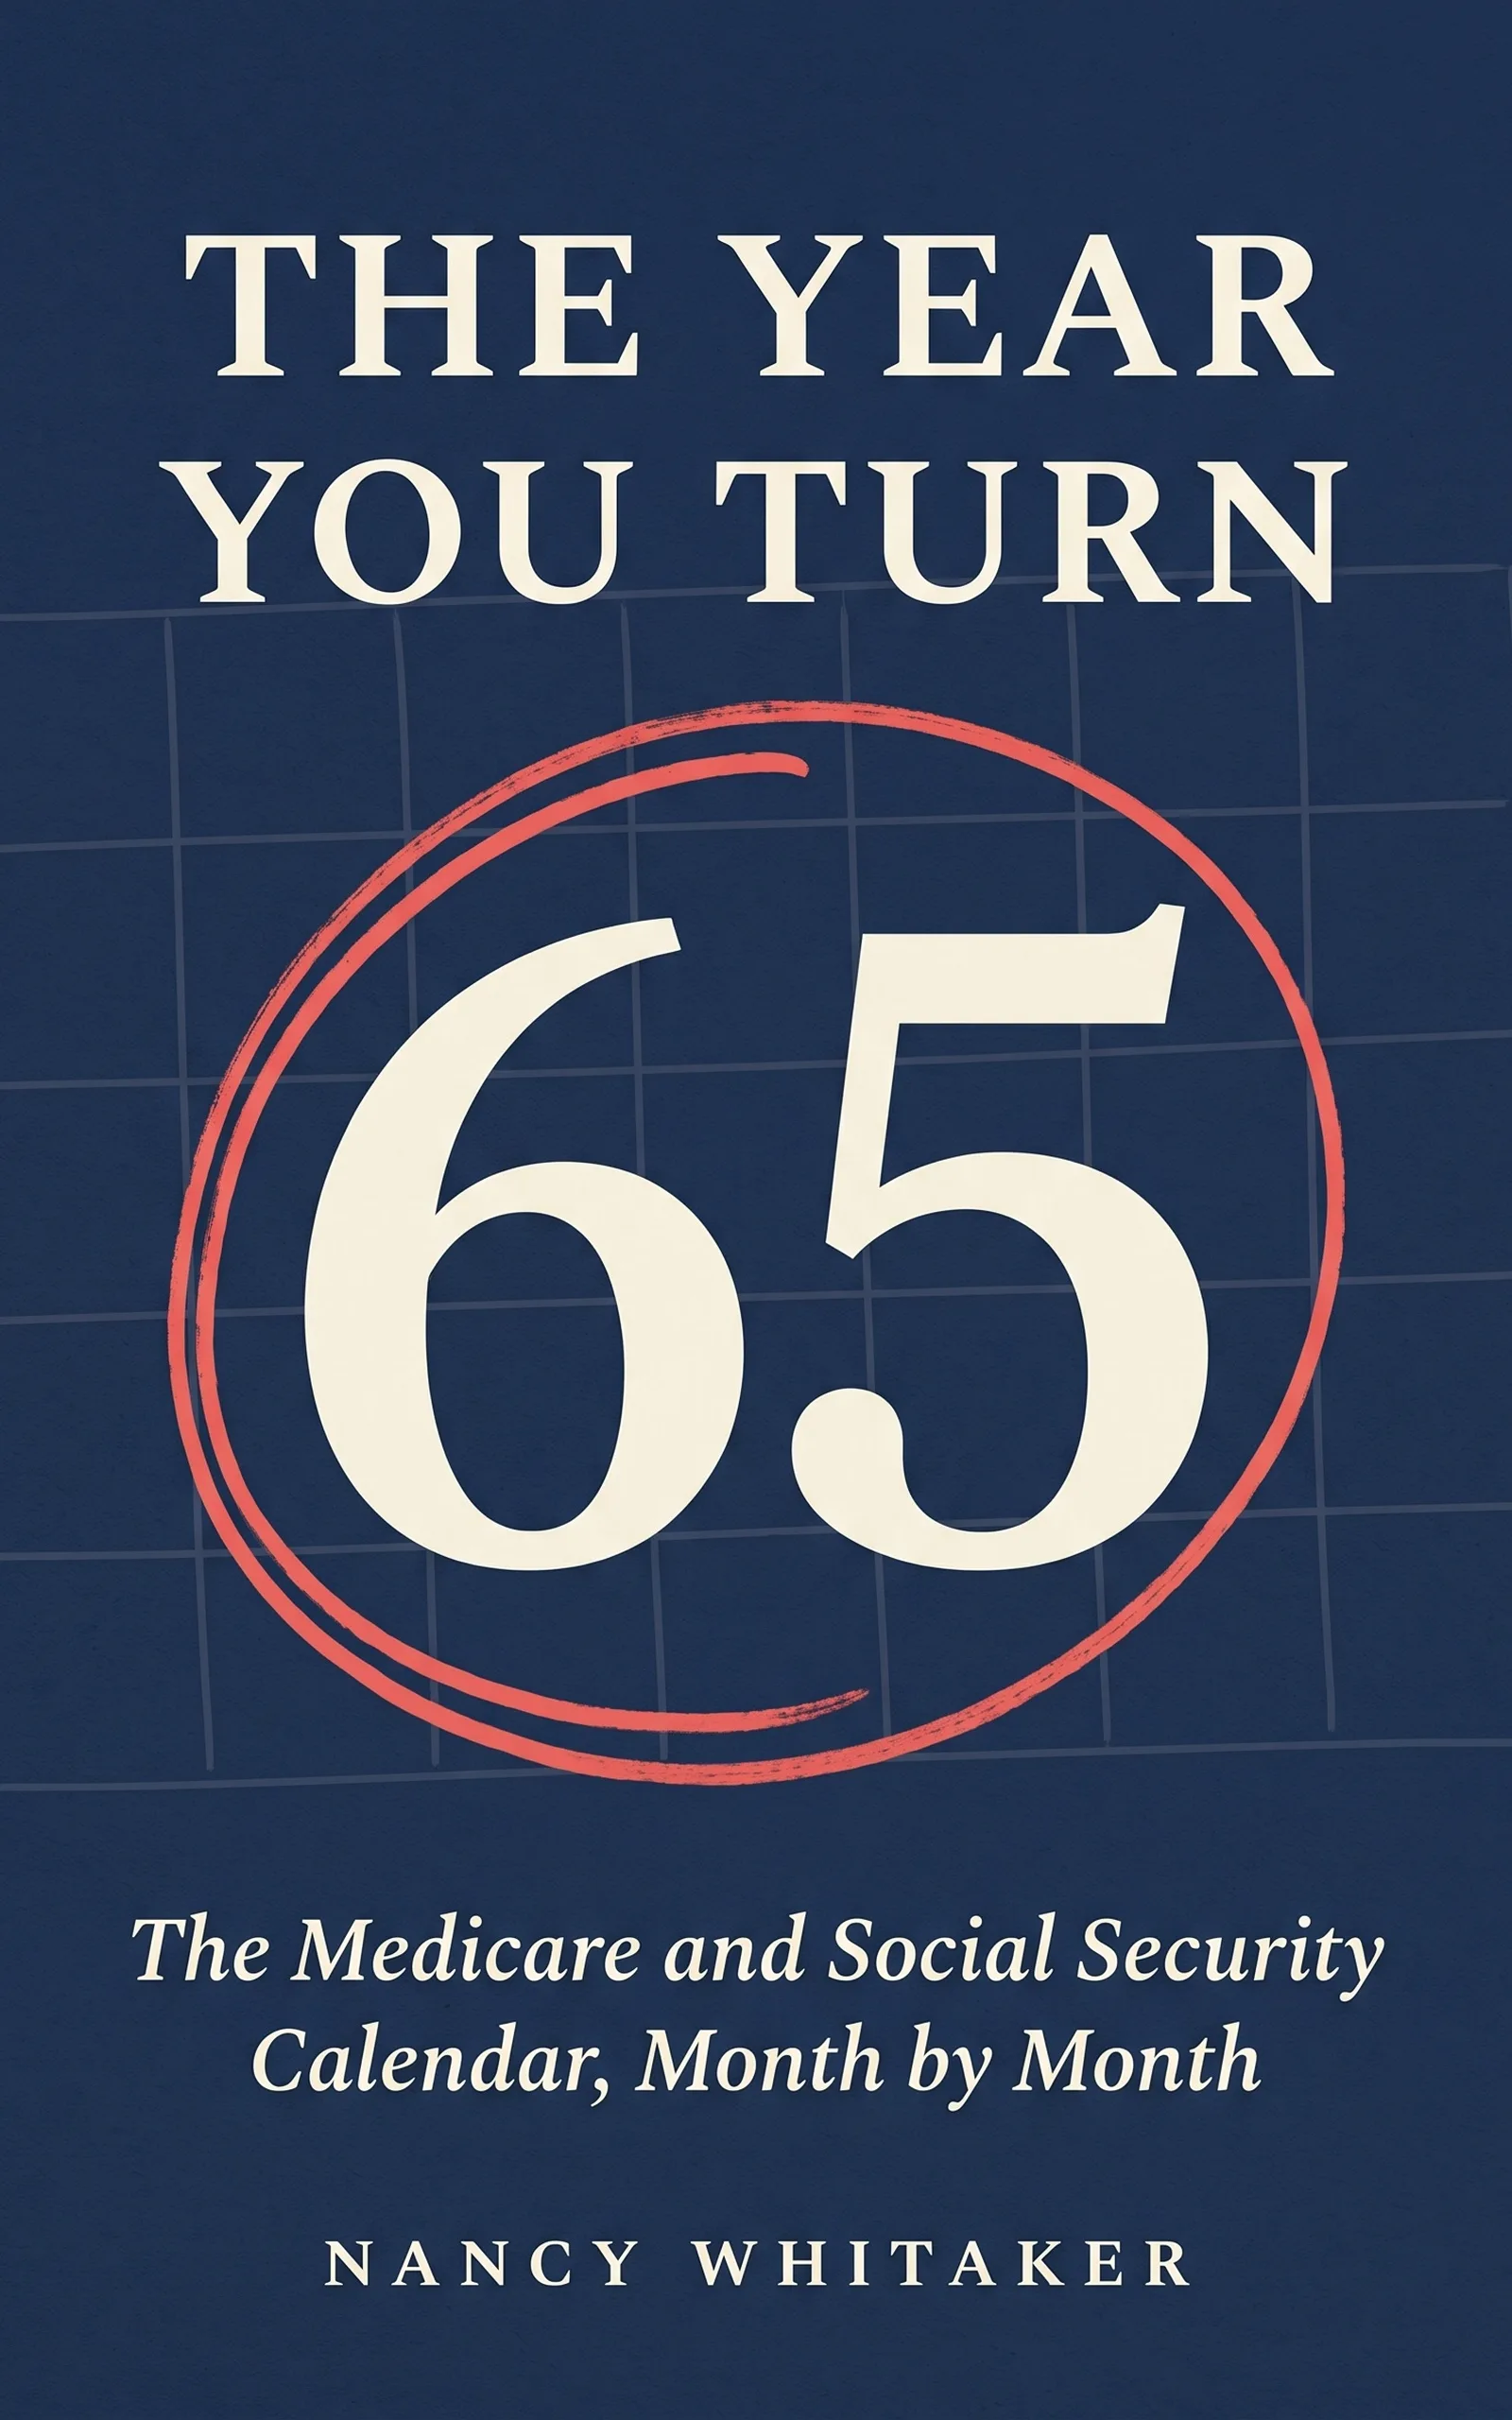
The book for this problem
The Year You Turn 65
The Medicare and Social Security Calendar, Month by Month. By Nancy Whitaker, 162 pages.
Where this problem is in the book:
- Three Months Out: The Seven-Month Window Opens
- The Same Window: The Drug Coverage Question
- The Month You Turn 65
- Your 65 Calendar
Links go to Amazon. ToolGenX publishes this book under a pen name and earns from every sale. Amazon sets the price and handles delivery and returns.
Is The Year You Turn 65 the right book for you?
Yes, if
- Your 65th birthday month is three months away, or closer
- You want one list of what to do, in order, instead of ten web pages
- You are helping a parent through the months around their 65th birthday
Skip it if
- You want to be told which plan to pick (this is a list of steps, not choices)
- You turned 65 more than three months ago (start with the missed sign-up page)
Fair doubts before you buy
Why not use a free checklist from an insurance company?
You can. Just notice who made it and what it leads to. This book sells nothing and names no plan. Every step comes from Medicare, CMS, Social Security or the IRS, with the date it was checked.
Is three months enough time to do all this?
For the sign-up itself, yes. The window stays open three more months after your birthday month. The steps that take longer, like fixing a wrong year on your earnings record, belong earlier, which is why the book starts twelve months out.
Get The Year You Turn 65
Turning 65 starts several clocks nobody mails you; the book lines them up month by month from your own birthday, with every number sourced.
Links go to Amazon. ToolGenX publishes this book under a pen name and earns from every sale. Amazon sets the price and handles delivery and returns.
Not affiliated with Medicare, the Social Security Administration, or any government agency. This book lays out published rules and dates. It is not legal, tax, medical or financial advice. For your own record, call your State Health Insurance Assistance Program (SHIP) or Social Security.
Questions people ask about this
- Should I sign up for Medicare 3 months before I turn 65?
- The book does not tell you when to sign up, but it gives the rule. Three months before your birthday month is when the window opens. If you sign up in the first three months, Part B starts in your birthday month. If you sign up in your birthday month or the three after, it starts the month after you apply.
- Will Medicare sign me up automatically at 65?
- Only if you have been getting Social Security or Railroad Retirement benefits for at least 4 months before you turn 65. Then the card arrives by mail about 3 months before coverage starts. Otherwise you sign up yourself.
- Do I need a Part D drug plan at 65 if I take no medicine?
- That is your choice. The rule is that a penalty starts building if you go 63 days or more in a row without Medicare drug coverage or other creditable coverage after your first window ends. In 2026, twenty uncovered months would add $7.80 a month.
- What should I check on my Medicare card when it arrives?
- Check that the details are right and note the start dates for Part A and Part B. Guard the Medicare Number on it. Then put the card in the same folder as your sign-up proof and any coverage letters.
- What documents should I keep when I sign up for Medicare?
- Proof of the date you signed up, such as the online confirmation or the name of the person you spoke with. Also keep creditable drug coverage letters, any employer letter on company size, and letters that end job, COBRA or retiree coverage.
- Can I sign up for Medicare by phone?
- Social Security handles sign-up for Part A and Part B. You can sign up online at SSA.gov/medicare/sign-up, or contact Social Security 3 months before you turn 65 to set up an appointment. Its phone number is 1-800-772-1213 (TTY 1-800-325-0778). If you worked for a railroad, go through the Railroad Retirement Board instead.
Related problems
- When do you sign up for Medicare at 65? The seven-month window, month by month
Your Medicare sign-up window is seven months long and built around your birthday. See when it opens, when it closes and when Part B starts.
- Original Medicare vs Medicare Advantage: how the two paths compare, side by side
A plain side-by-side of Original Medicare and Medicare Advantage: doctors, yearly cap, cost, extras, approvals and the rules for switching back.
- When to stop HSA contributions before Medicare: the six months that reach backward
Part A can start up to 6 months before you apply, and HSA money put in for those months is excess. Count your last safe month, step by step.
- Your Medicare premium letter says you owe more because of income you no longer have
An IRMAA surcharge is set from your tax return from 2 years ago. If your income dropped after retiring, Form SSA-44 asks for a newer year.
- Everything inside The Year You Turn 65
Every chapter, who the book is for, and every problem it helps with.