Last updated
I'm healthy at 65. Can I wait and buy Medigap later? The six-month window that comes once
You feel fine, and extra insurance feels like paying for nothing
You signed up for Original Medicare. You feel good. You see a doctor once a year, maybe twice.
A Medigap quote lands in the mail. It is one more monthly premium on top of Part B. You think, sensibly, that you will look at it later if something comes up.
Most people think the same thing. And most people assume "later" works the same as "now."
Now picture two years on. A diagnosis. You apply for a Medigap policy. This time the company asks about your health. It quotes a price you can't pay, or it says no.
That can happen because a one-time window closed while you weren't looking.
Why "you can always add it later" is wrong for Medigap
Plenty of coverage works on a yearly cycle. Drug plans do. Advantage plans do. Every fall, October 15 to December 7, you can switch.
So it is natural to think Medigap does too. It does not. The fall windows do not give you a federal right to buy Medigap.
Here is the rule in the official guide, written by Medicare and the National Association of Insurance Commissioners: "Your 6-month Medigap Open Enrollment Period starts the first month you have Medicare Part B and you're 65 or older. This is a one-time enrollment period; it doesn't repeat every year."
During those 6 months, a company must sell you any Medigap policy it offers in your state. It can't turn you down for your health. It can't charge you more for your health.
After the 6 months, those protections end for most people. The guide adds that the window "can't be changed or repeated." Once Part B starts after 65, the 6 months run whether you buy a policy or not.
Find your own six months, then decide
Here is the one idea worth taking from this page. Before you decide anything about Medigap, write down the month your window closes.
The window starts when two things are true: you have Part B, and you are 65 or older. For most people that is the month they turn 65. Count six months from there.
If you put off Part B because you have coverage from a current job, your window waits too. The guide says that when you sign up for Part B later, "your Medigap Open Enrollment Period will start when you're ready to take advantage of it." This case is easy to miss, so we flag it: the window did not start at 65.
Some details inside the window:
- Health problems you already have. A policy may make you wait up to 6 months before it covers a problem you had before it started. If you had at least 6 months of steady health coverage before, with a break of no more than 63 days, the wait may not apply.
- Plans C and F. If you became eligible for Medicare on or after January 1, 2020, you can't buy them. The other lettered plans are still sold.
- Plan letters. In most states plans are named A through D, F, G, and K through N. Every plan with the same letter has the same basic benefits, whatever company sells it.
The full Choosing a Medigap Policy guide has the details for each letter.
If you are healthy, look at prices while the window is open
Being healthy is a good time to compare, because inside the window your health can't change the price. A few facts help when you start.
- Each company sets its own price. Medicare's Medigap cost page says each insurance company decides how it will set the premium. Two policies with the same letter can cost quite different amounts.
- The benefits match, the price does not. Every plan with the same letter has the same basic benefits, whichever company sells it. The handbook says costs can vary "for exactly the same coverage, and may go up as you get older."
- Some companies give discounts. Medicare lists examples such as paying once a year, paying electronically, or having more than one policy with the company.
- You pay it on top of Part B. The Medigap premium goes to the private company. Your Part B premium still goes to Medicare.
You can look up the Medigap policies sold where you live on Medicare.gov. A SHIP counselor can also help you compare them for free.
The later chances that do exist
The window is not the only door. It is the widest one.
Federal law gives a few more chances to buy Medigap without health questions. In most of them you must apply within 63 days after your old coverage ends. They include an Advantage plan leaving your area, a job-based plan that pays after Medicare ending, and a Medigap company going bankrupt.
Two of them are trial rights, for people who try Medicare Advantage and change their mind. If you joined an Advantage plan when you first got Part A at 65, and you leave within the first year, you can buy any Medigap policy sold in your state. For both trial rights, you can apply as early as 60 days before your plan coverage ends and no later than 63 days after.
Some states add more. New York requires insurers to accept a Medicare enrollee's application "at any time throughout the year." California has a 60-day window after your birthday each year to switch to a policy with the same or fewer benefits. Oklahoma's insurance department describes a 60-day window that begins on your birthday. These birthday rules help people who already have Medigap and want to switch. They don't help a first-time buyer.
Keep the paperwork. The guide tells people to keep ending letters, claim denials and even the postmarked envelope as proof of dates.
The chapter that tracks this window
This is the problem The Year You Turn 65 was written for. Nancy Whitaker gives the window its own chapter, because it only runs once.
The Month Part B Starts: The Six Months Medigap Gives You Once has the rule in the guide's own words, what starts the clock, the waiting period, Plans C and F, every protected right with its dates, both trial rights and the three state rules the book checked on the states' own websites.
Before You Choose: Original Medicare or Medicare Advantage shows why going back to Original Medicare does not promise you a Medigap policy.
Still Working at 65 explains how putting off Part B moves your Medigap window with it.
The book is not affiliated with Medicare or Social Security, and it does not tell you whether to buy. Your State Health Insurance Assistance Program (SHIP) gives free counseling on Medigap plans, and your State Insurance Department can tell you about your state's extra windows. Social Security can confirm the date your own Part B starts.
The book for this problem
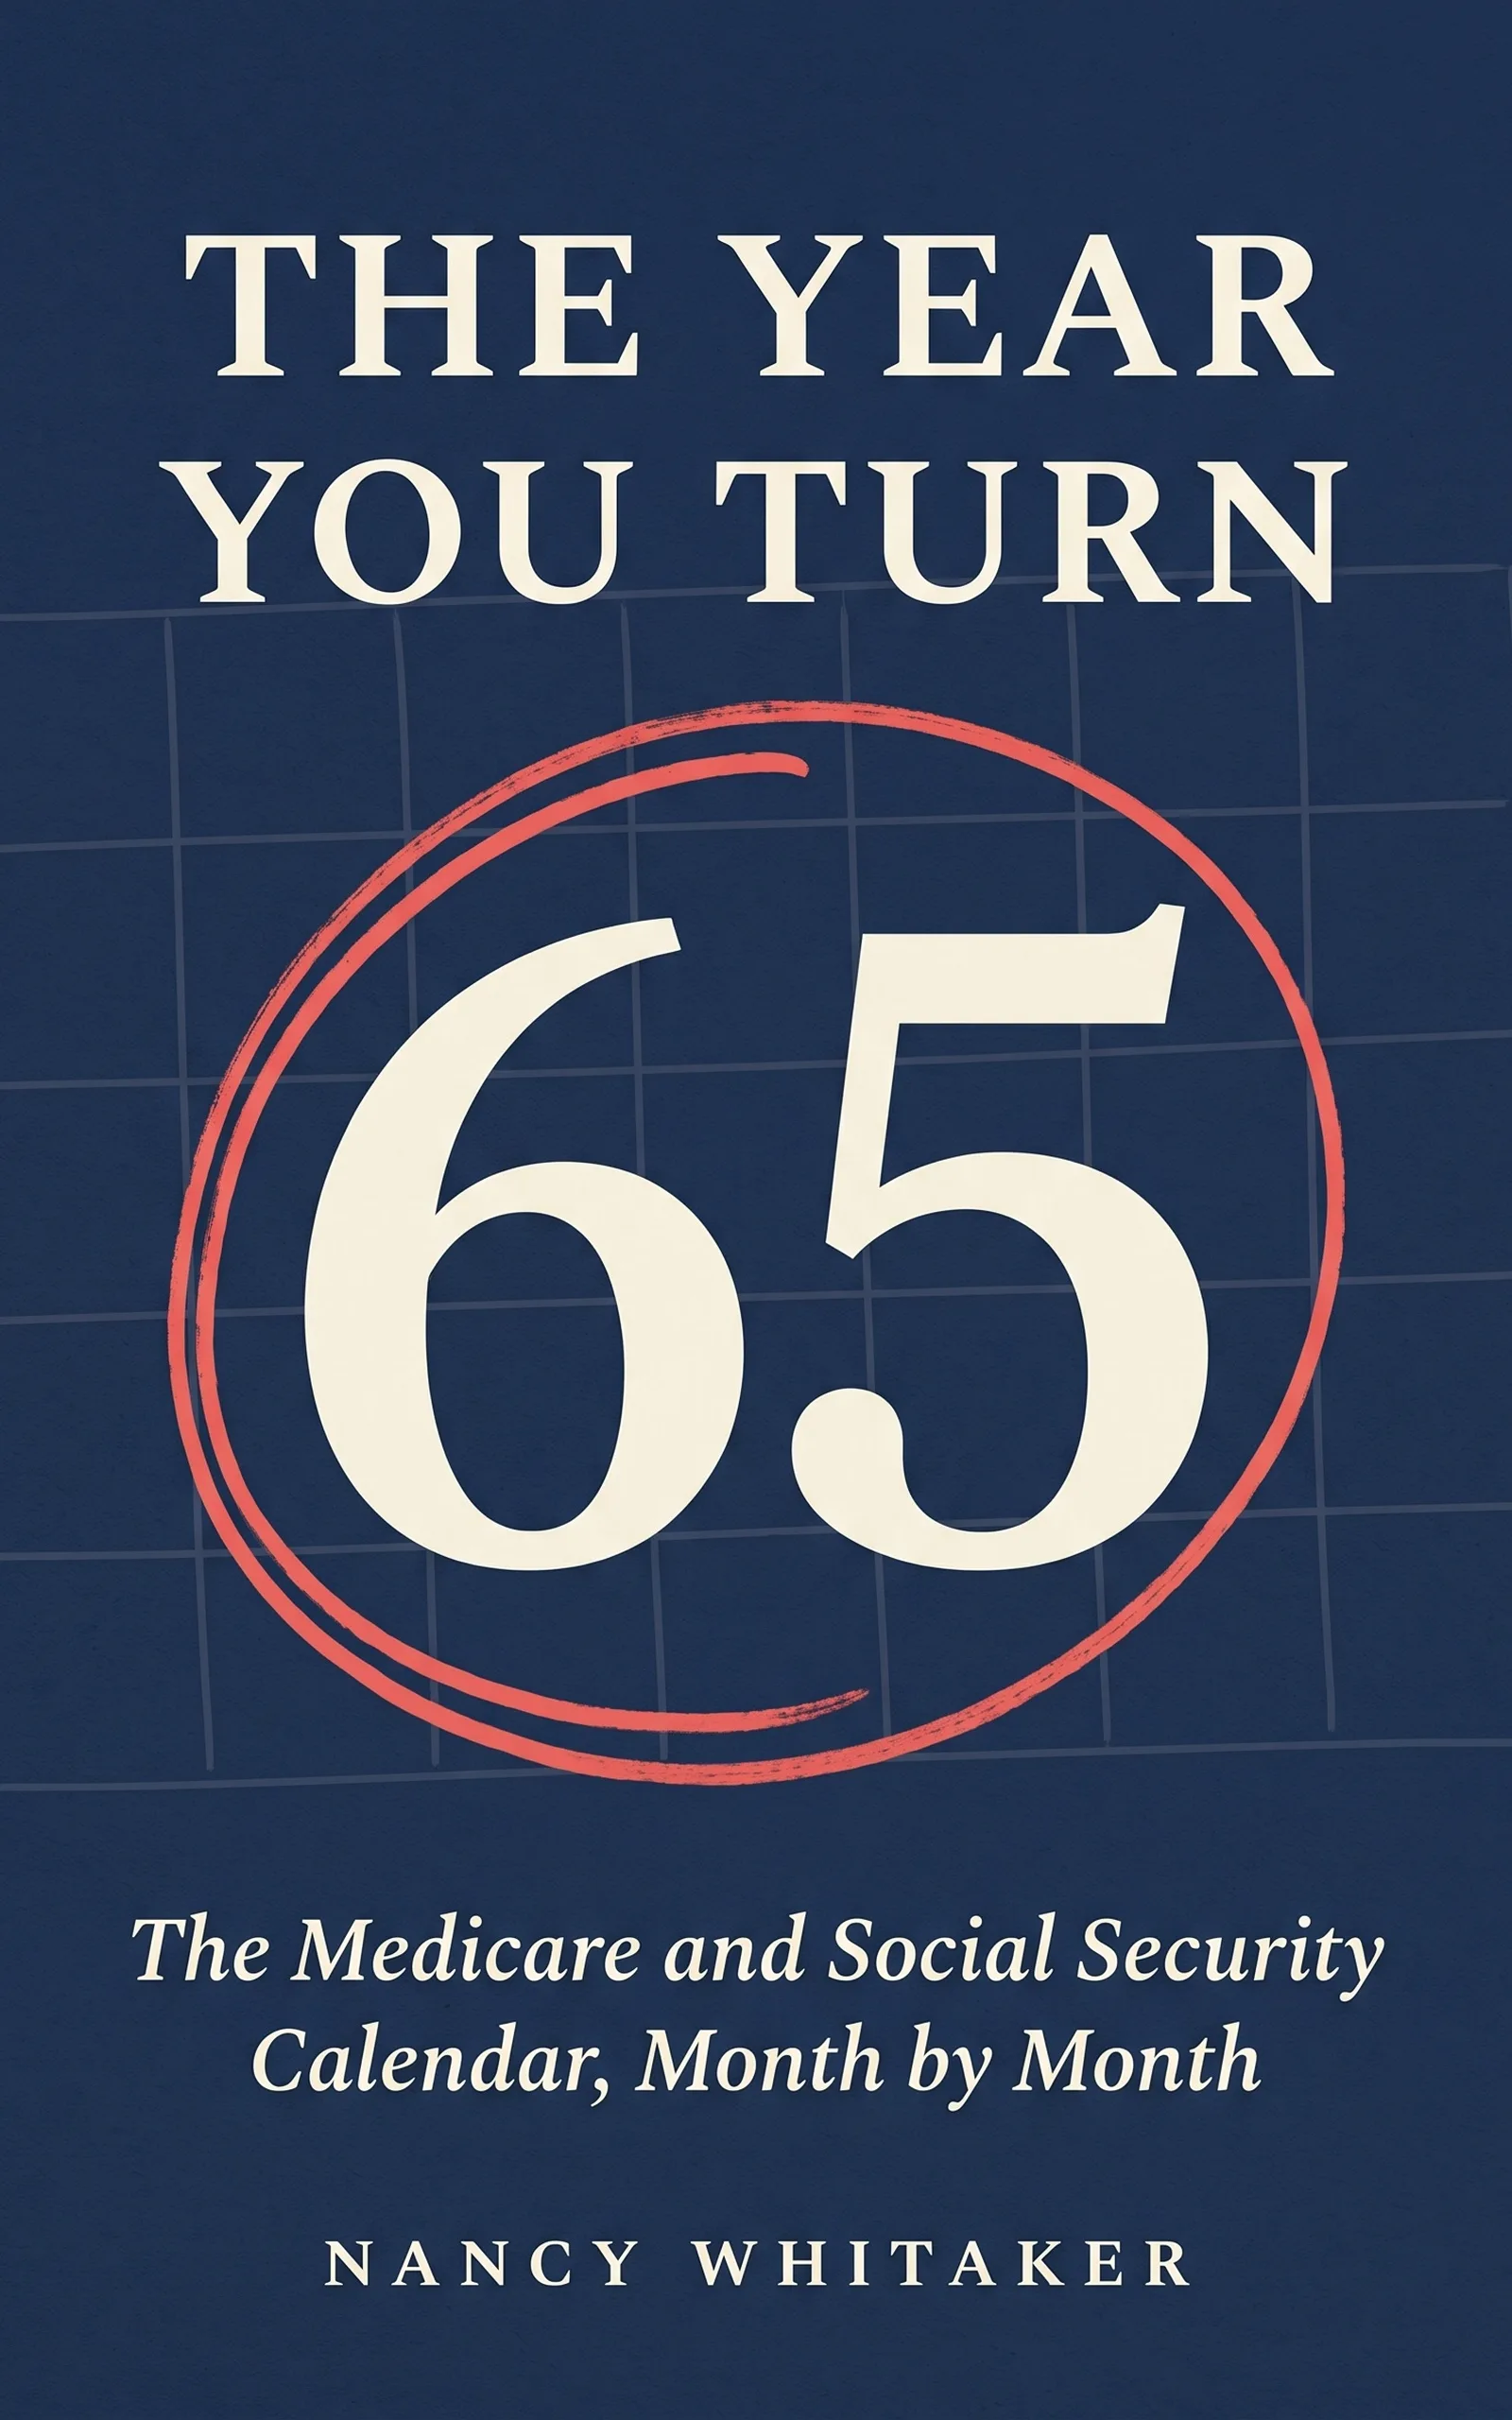
The Year You Turn 65
The Medicare and Social Security Calendar, Month by Month. By Nancy Whitaker, 162 pages.
Where this problem is in the book:
- The Month Part B Starts: The Six Months Medigap Gives You Once
- Before You Choose: Original Medicare or Medicare Advantage
- Still Working at 65
Links go to Amazon. ToolGenX publishes this book under a pen name and earns from every sale. Amazon sets the price and handles delivery and returns.
Is The Year You Turn 65 the right book for you?
Yes, if
- You are choosing Original Medicare and wonder whether Medigap can wait
- You put off Part B because of a job and want to know when your Medigap window starts
- You are thinking about trying Medicare Advantage first and want to know the way back
Skip it if
- You want to be told whether to buy Medigap or which letter plan to pick
- You live in Massachusetts, Minnesota or Wisconsin and need those states' own plan names
Fair doubts before you buy
Isn't this just scaring people into buying insurance?
The book sells no insurance and names no company. It quotes the rule from the official Medigap guide and leaves the choice with you. Some people buy, some don't. The point is to know the window exists while it is still open.
Can't the insurance company just tell me the rules?
It can tell you its own rules. The federal window is set by Medicare, and some extra rights come from your state. Your State Insurance Department and your State Health Insurance Assistance Program (SHIP) can tell you what applies where you live, and SHIP is not connected to any insurance company.
Get The Year You Turn 65
Turning 65 starts several clocks nobody mails you; the book lines them up month by month from your own birthday, with every number sourced.
Links go to Amazon. ToolGenX publishes this book under a pen name and earns from every sale. Amazon sets the price and handles delivery and returns.
Not affiliated with Medicare, the Social Security Administration, or any government agency. This book lays out published rules and dates. It is not legal, tax, medical or financial advice. For your own record, call your State Health Insurance Assistance Program (SHIP) or Social Security.
Questions people ask about this
- When does the Medigap open enrollment period start?
- The first month you have Medicare Part B and are 65 or older. For most people that is the month they turn 65. If you put off Part B because of coverage from a current job, the window waits until your Part B starts.
- Can I be denied a Medigap policy after open enrollment?
- Yes, in most cases. After the 6 months end, a company can review your health before selling you a policy. That can mean a higher price or a no. The exceptions are a short list of federal protected rights and any extra rights your state gives.
- Does the Medigap window repeat every year?
- No. The official guide calls it a one-time enrollment period that doesn't repeat every year. It also says the window can't be changed or repeated. The fall Medicare windows do not give a federal right to buy Medigap either.
- Can I still buy Medigap Plan F?
- Not if you became eligible for Medicare on or after January 1, 2020. People in that group can't buy Plan C or Plan F. The other lettered plans are still sold.
- Is there a waiting period for pre-existing conditions with Medigap?
- There can be. Even inside the window, a policy may make you wait up to 6 months before it covers a health problem you had before it started. If you had at least 6 months of continuous health coverage before, with a break of no more than 63 days, that wait may not apply.
- What if I am healthy and want to try Medicare Advantage first?
- You can, and there is one protection for that. If you joined a Medicare Advantage plan when you first became eligible for Part A at 65, and you leave within the first year, you can buy any Medigap policy sold in your state without health questions. That is the trial right. Apply no later than 63 days after your plan coverage ends. After that first year, it is much harder.
Related problems
- Original Medicare vs Medicare Advantage: how the two paths compare, side by side
A plain side-by-side of Original Medicare and Medicare Advantage: doctors, yearly cap, cost, extras, approvals and the rules for switching back.
- Still working at 65: can you delay Medicare Part B? Start with the size of your employer
Whether you can put off Part B while working depends on one number: 20 employees. See who pays first, the 8-month window and the forms.
- What to do 3 months before turning 65: a month-by-month Medicare checklist
Three months before your 65th birthday month, your Medicare window opens. A month-by-month checklist of what to do, from a year out to after.
- Everything inside The Year You Turn 65
Every chapter, who the book is for, and every problem it helps with.